Institutional 4-Phase Advisory Architecture • Florida OIR #L104928

How It Works: Our Fiduciary Insurance Methodology

A systematic, actuarial process engineered for clinical provider matching, statutory subsidy optimization, side-by-side plan audit, and lifelong policyholder advocacy across Florida.

Phase 01: Intake Phase 02: Subsidies Phase 03: Audit Phase 04: Advocacy
Fiduciary Representation

A Scientific Alternative to Call Centers & Web Algorithms

Navigating Florida's complex health and life insurance landscape should never rely on impersonal aggregator algorithms or captive telephone agents incentivized by sales quotas.

Assertive Insurance operates as an Independent General Agency. Our fiduciary code prioritizes your family's doctors, clinical safety, and household tax efficiency across Florida's leading admitted carriers—delivering complete transparency with guaranteed statutory rate parity.

Direct Provider NPI Auditing We verify specific physician and hospital National Provider Identifier (NPI) credentials directly in active carrier databases before application submission.
Mathematical Subsidy Engineering We model household MAGI against the Second Lowest Cost Silver Plan benchmark to maximize tax credits and unlock Cost-Sharing Reductions.
Year-Round Claims Advocacy Our advisory role continues for the life of your policy. If hospital denial notices occur, our desk intervenes directly under the No Surprises Act.
Begin Phase 1 Discovery Call Advisor Desk
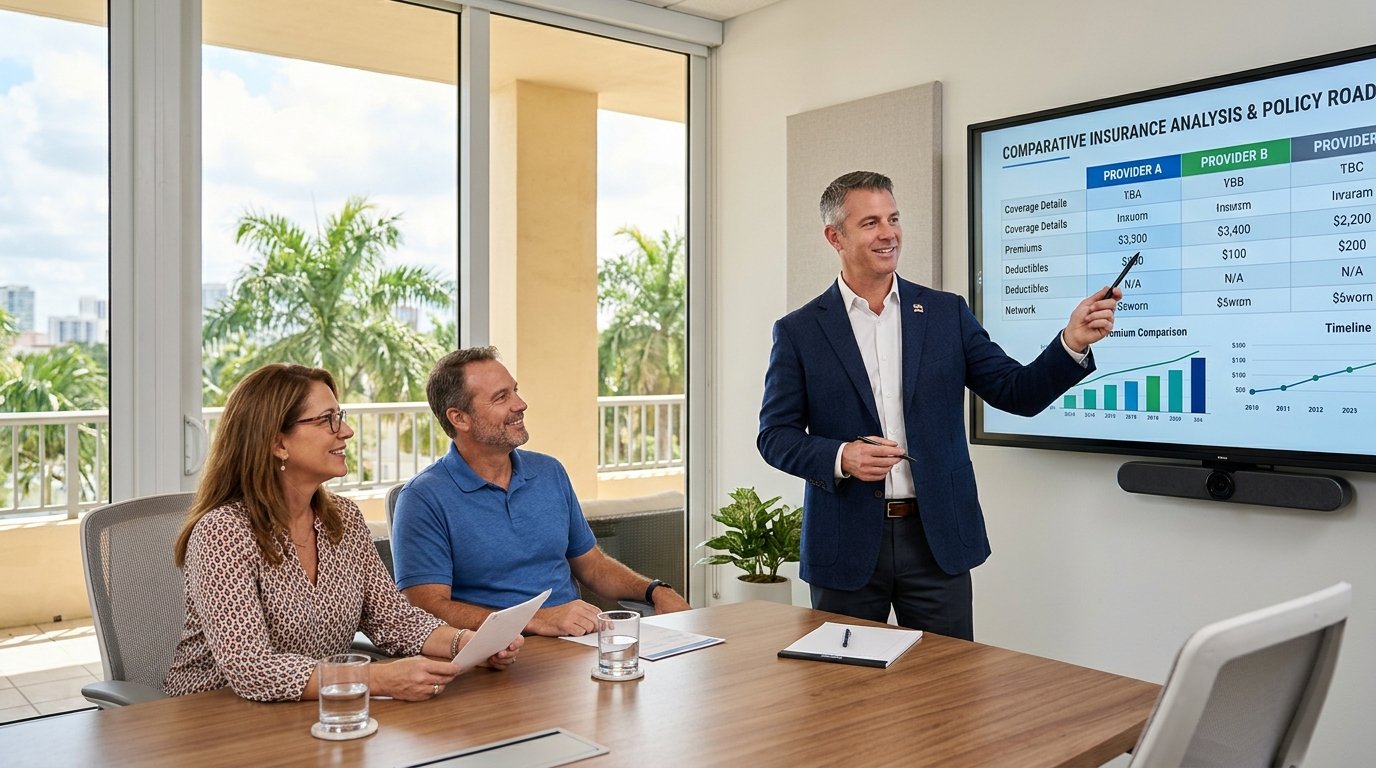
Licensed Florida insurance advisor explaining comparative plan roadmap to clients
Direct Appointed Florida Agency Licensed Across All 67 Florida Counties • Zero Broker Markups
Comprehensive Architecture

The 4-Phase Advisory Lifecycle in Detail

A transparent breakdown of each operational stage, statutory verification protocol, and client deliverable.

01 Phase
Phase 01 Clinical & Demographic Discovery
Florida Statute § 626 Fiduciary Standard

Census Intake, Clinical NPI Cross-Matching & Tax Architecture

Our advisory process begins with a structured census intake. Rather than collecting superficial contact info, we evaluate the exact actuarial variables governing health outcomes and fiscal exposure:

•
Physician NPI Registry Match: We lookup your primary care doctors and specialists against active Florida Blue, Aetna, UHC, Cigna, and Oscar rosters to guarantee zero network disruption.
•
Hospital System Continuity: Direct verification of contracted access to Baptist Health, Memorial Healthcare, Cleveland Clinic Florida, Mount Sinai, and Holy Cross.
•
Tax Classification Architecture: Calibration based on 1099 self-employment, W-2 payroll, S-Corp K-1 distributions, or retirement transition milestones.
•
Formulary NDC Medication Audit: Auditing daily maintenance prescriptions against Tiers 1 through 5 to eliminate unexpected specialty coinsurance.
Phase 1 Deliverable: Certified Clinical & Actuarial Census Summary with confirmed in-network hospital systems and validated formulary NDC codes.
Discovery Audit Specification
CERTIFIED
100%
NPI Doctor Match
Area 6 / 11
Florida Rating Area
Tiers 1–5
Formulary NDC Check
IRC § 125 / 223
Tax Compatibility
Florida Clinical Network Guarantee: Your personal doctors and hospital facilities are verified live in active carrier appointment rosters before any application is generated.
02 Phase
Phase 02 Multi-Carrier Traversal & Tax Engineering
IRC § 36B & IRC § 45R Benchmark

Multi-Carrier Actuarial Traversal & Subsidy Optimization Engine

With clinical parameters locked, our advisory desk scans 50+ plan filings across Florida's admitted carriers. We apply advanced mathematical algorithms to calculate exact tax credit entitlements:

•
APTC Benchmark Calibration: Modeling household MAGI against the Second Lowest Cost Silver Plan (SLCSP) to calculate maximum Advance Premium Tax Credits under IRC § 36B.
•
Cost-Sharing Reduction (CSR) Unlocking: Targeting Silver variants (73%, 87%, and 94% Actuarial Value) that slash deductibles by thousands without increasing monthly premiums.
•
Corporate Level-Funded Underwriting: For groups with 5 to 200 staff, comparing fully-insured rates against level-funded stop-loss designs featuring 100% claims surplus refunds.
•
Pre-Tax Section 125 POP Integration: Setting up salary reduction cafeteria plans that eliminate 7.65% FICA payroll taxes on employee-paid health contributions.
Phase 2 Deliverable: Actuarial Tax & Subsidy Matrix displaying gross premiums, federal credits, and net monthly out-of-pocket costs.
Actuarial Subsidy Engine Matrix
CALCULATED
SLCSP
Federal Benchmark
94% AV
Max Silver CSR Level
7.65%
Payroll FICA Savings
IRC 45R
Small Biz Tax Credit
Mathematical Subsidy Engineering: Ensures zero forfeited tax credits under federal ACA formulas while verifying non-cliff safe harbors during income fluctuations.
03 Phase
Phase 03 Formal Comparative Audit & Selection
Fla. Stat. § 627.410 Rate Parity Guaranteed

Formal Comparative Audit & Multi-Tier Customization

Insurance transparency requires seeing competing policies side-by-side. Our advisory desk prepares a standardized comparison report decoding complex fine print:

•
Metallic Tier Breakdown: Transparent comparison across Bronze (60% AV), Silver (70–94% AV), Gold (80% AV), and Platinum (90% AV) based on anticipated clinical utilization.
•
Embedded vs. Aggregate Deductibles: Mathematical modeling demonstrating how embedded individual safety caps protect household budgets during severe medical events.
•
Out-of-Pocket Maximum (MOOP) Exposure: Clear disclosure of total worst-case catastrophic financial liabilities under each carrier plan.
•
Zero Broker Markups Guarantee: Under Florida Insurance Code § 627.410, rates are strictly identical whether enrolling through our brokerage or directly with an insurer.
Phase 3 Deliverable: Side-by-Side Corporate Comparative Disclosure Schedule with transparent deductible, copay, and network comparisons.
Corporate Comparison Matrix
AUDITED
$0.00
Broker Fee / Markup
Embedded
Individual Safety Cap
50+ Plans
Florida Carrier Filings
Side-by-Side
Comparative Format
Rate Parity Legal Guarantee: Premiums are legally filed with the Florida Office of Insurance Regulation. You never pay a penny extra for our licensed fiduciary advocacy.
04 Phase
Phase 04 Direct Inception & Lifetime Claims Advocacy
Federal No Surprises Act Protection

Direct Electronic Inception & Lifelong Fiduciary Advocacy

Unlike lead generators who sell your contact details to dozens of call centers and disappear, our fiduciary commitment begins the moment your policy is bound:

•
Direct Electronic Underwriting Submission: Electronic binding directly through carrier general agency portals with immediate confirmation and policy issuance.
•
Member Onboarding & ID Card Expediting: Confirmation of premium processing, digital member ID cards, and portal credentials.
•
No Surprises Act Claims Defense: If a hospital or surgical facility sends an unexpected balance bill, our Hollywood desk intervenes directly under federal consumer protection laws.
•
Proactive Annual October Recalibration: Automated audit of your rate filings and network updates every fall before Open Enrollment.
Phase 4 Deliverable: Active policy binding certificate, digital member ID issuance, and ongoing fiduciary advocacy.
Policy Inception & Claims Defense
ACTIVE ADVOCACY
Direct API
Electronic Inception
Protected
No Surprises Act
Hollywood FL
Local Physical Desk
October Audit
Annual Recalibration
Lifelong Fiduciary Advocacy: Your dedicated Hollywood, Florida advisor defends claims, resolves billing errors, and shops the market every autumn for life.
Institutional Comparison

Comparing Insurance Advisory Channels

Understanding the legal, actuarial, and service differences between an Independent General Agency, a single-company captive agent, and automated lead aggregator sites.

Service & Governance Feature
★ Recommended Institutional Path
Assertive Insurance (Independent General Agency)
Captive Agent (State Farm, etc.) Direct Web Aggregator (Direct Portals)
Legal Fiduciary Alignment Bound to single insurer Lead reseller algorithm
Carrier Market Access Only 1 proprietary line High manual input burden
Physician NPI Registry Auditing Only checks single roster Self-serve directory errors
Rate Guarantee & Consultation Fee Fixed rate (1 carrier) Identical rate with 0 defense
Billing & Denial Claims Defense Limited corporate support Outsourced overseas call queue
Annual October Renewal Recalibration Can only reduce your benefits Client left completely alone
Advisory Intelligence

Process Governance & Fiduciary Hub

Common questions regarding broker compensation, binding speed, network continuity, and claims advocacy.

Statutory Pricing Fla. Stat. § 627.410

Does working with Assertive Insurance cost more than enrolling directly?

Under Florida Insurance Code, insurance premium rates are filed, actuarially approved, and legally fixed by state authorities:

Guaranteed Rate Parity: An insurance carrier cannot legally discount a policy because you enroll on their direct website or telephone number.
Built-In Advisory Value: Carrier compensation is legally standardized and built into the rate filing. You receive personalized fiduciary representation with zero extra fees.
Advisory Note: Enrolling directly on an aggregator website forfeits a dedicated claims advocate with zero reduction in your monthly bill.
Inception Timelines 45 CFR § 155.420

How quickly can our health or group coverage be bound and active?

Policy binding timelines depend on the specific line of coverage and enrollment triggering event:

Individual ACA / SEP: Applications bound through Special Enrollment Periods can become effective on the first day of the following calendar month.
Corporate Small Group: Typical group census to policy inception requires 10 to 14 business days, with expedited 48-hour turnarounds available.
Life & Term Insurance: Accelerated digital underwriting approvals in 24 to 48 hours for qualifying applicants without in-person medical exams.
Advisory Note: In emergency situations or off-cycle transitions, our licensed brokers execute priority carrier underwriting queues.
Network Continuity FL OIR Rule 69O-191

What happens if my doctor or local hospital leaves the network mid-year?

Under Florida Insurance Code, strong policyholder continuity protections exist when hospital-carrier contracts change:

Continuity of Care Mandate: Enrollees undergoing active course of treatment (pregnancy, oncology, scheduled surgeries) are legally permitted to continue care at in-network rates for up to 90 days.
Broker Facilitated Transition: Our advocacy desk prepares the required continuity filings and cross-matches accredited clinical specialists in your immediate community.
Advisory Note: Notify Assertive Insurance immediately if your clinic announces a carrier termination so our team can protect your claims.
Annual Recalibration Annual October Audit

How does Assertive Insurance manage annual renewals and rate shifts?

Insurance carriers adjust rates, formularies, and provider contracting every calendar year. We manage annual renewal auditing proactively:

Automated Renewal Audit: In October, our system cross-checks your current plan against all newly approved Florida carrier rate filings.
Zero-Friction Transition: If a competing carrier offers lower premiums with identical hospital networks, we manage the seamless transition with zero gap in coverage.
Advisory Note: Annual policy reviews are 100% complimentary and included as part of your ongoing relationship with our agency.
Start Your Advisory Journey

Experience the Assertive Advisory Difference

Get customized insurance plan comparisons across Florida's leading insurers with zero fee, zero markup, and zero high-pressure sales calls.
Start Phase 1 Discovery Call Advisor Desk: +1 (305) 709-6984