Independent American Insurance Agency

Confidence Starts with the Right Coverage

Explore insurance solutions designed around your needs, your family, and your business. Get personalized guidance from licensed Florida advisors to help you make informed coverage decisions with zero pressure.

Florida-Licensed Advisors
Multi-Carrier Comparisons
Zero Brokerage Markups
Assertive Insurance healthcare advisor consulting an American family
Direct Plan Access
Tailored options for Florida individuals, families, & employers
100%
Independent Advocacy
Hollywood, FL
Headquarters & Local Presence
Top Tier
Major Carrier Plan Networks
Mon – Fri
Dedicated Client Consultation
Plan Finder

Find the Right Coverage for Your Stage of Life

Insurance isn't a one-size-fits-all product. Select your current life situation below to explore recommended plan structures, tax incentives, and cost-saving opportunities.

Personal Medical Guidance

Tailored Coverage for 1099 Contractors & Freelancers

When you are self-employed or work without employer benefits, selecting health insurance requires balancing monthly premiums with doctor access. We check if your projected household income qualifies for Advance Premium Tax Credits (APTC) that lower monthly payments drastically.

  • ✓ ACA Marketplace Subsidies: Save hundreds monthly depending on your income tier.
  • ✓ HSA-Qualified Plans: Pair High-Deductible Health Plans with triple-tax-advantaged savings.
  • ✓ PPO Specialist Freedom: Choose plans that don't require gatekeeper PCP referrals.
Actuarial Profile IRC § 162(l) / ACA § 1302

Individual Actuarial Specifications

Optimal Plan Tier Silver 87-94% AV (CSR)
Avg Net Premium $18 – $65 / month
Tax Shelter 100% Tax Deductible
Preventive Copay $0 Copay Mandate
Network Verification: Direct doctor NPI cross-matching across Florida Blue, Oscar Health, Ambetter, and Aetna CVS Health.
Household Wellness

Protecting Both Parents and Children Under One Plan

Family plans must handle everything from routine pediatric vaccinations and developmental screenings to unexpected sports injuries. We examine embedded deductibles to ensure one family member's medical care doesn't force you to pay the entire family deductible out-of-pocket.

  • ✓ 100% Free Preventive Pediatric Care: $0 copays for routine checkups and vaccines.
  • ✓ Embedded Deductibles: Individual safety caps inside the shared family limit.
  • ✓ Dental & Vision Bundles: Cost-effective add-ons for braces and annual vision exams.
Household Matrix Fla. Stat. § 627.6562

Family Coverage Specifications

Deductible Structure Embedded Safety Caps
Dependent Age Limit Covered to Age 26–30
Pediatric Dental & Vision 100% EHB Mandate
Family Glitch Fix Full Subsidy Relief
Pediatric Protection: $0 well-child exams, complete CDC immunization schedules, and zero-deductible pediatrician appointments.
Commercial Group Benefits

Competitive Employee Health Plans with Maximum Tax Write-offs

For Florida companies with 2 to 200+ employees, group health insurance is the #1 tool to attract and keep experienced staff. Employer-paid premiums are 100% tax-deductible as business expenses, and qualifying small businesses receive federal tax credits up to 50% under IRC Section 45R.

  • ✓ Level-Funded Options: Opportunity for annual surplus cash refunds if claims are low.
  • ✓ Section 125 Cafeteria Plans: Employees contribute pre-tax, lowering payroll taxes for both sides.
  • ✓ Turnkey HR Administration: We manage annual open enrollment and new hire onboarding.
Commercial Architecture ERISA Title I & IRC § 125

Group Benefit Specifications

Funding Architecture Level-Funded Stop-Loss
Surplus Claims Return Refunded to Company
Payroll FICA Relief 7.65% Pre-Tax POP
Small Business Tax Credit Up to 50% (IRC 45R)
Underwriting Thresholds: Guaranteed-issue for Florida businesses with 2 to 50 FTEs; customized composites for 50+ ALE employers.
Retirement Healthcare

Clear Guidance on Medicare Advantage & Medigap Supplements

Original Medicare leaves major gaps: 20% coinsurance with no annual cap, and zero coverage for dental, vision, or prescription drugs. We guide Florida seniors turning 65 through Medigap Plan G/Plan N and $0-premium Medicare Advantage options to safeguard retirement savings.

  • ✓ Medigap (Medicare Supplements): See any doctor nationwide who accepts Medicare.
  • ✓ Medicare Advantage (Part C): All-in-one HMO/PPO bundles with dental, vision & hearing.
  • ✓ Part D Prescription Formulation: We verify your exact medication tiers before enrolling.
Senior Medicare Hub Title XVIII CMS Rules

Medicare Advisory Specifications

Medigap Benchmark Plan G & Plan N
Part D Out-of-Pocket $2,000 Annual Cap
Specialist Referrals Zero Gatekeeper (Medigap)
National Acceptance ~93% of US Physicians
Open Enrollment Window: 6-month Medigap Guaranteed Issue window starting the month you turn 65 and enroll in Part B.
Financial Legacy

Term Life & Whole Life Protection for Family Security

Ensure that an unexpected tragedy never leaves your loved ones facing mortgage foreclosure or financial distress. We evaluate 10 to 30-year Term Life policies for income replacement alongside permanent Whole Life policies with guaranteed cash-value accumulation.

  • ✓ Tax-Free Lump-Sum Payouts: Benefits pass to beneficiaries 100% free of income tax.
  • ✓ Mortgage Payoff Coverage: Locks in fixed rates matching your 15 or 30-year loan balance.
  • ✓ Accelerated Underwriting: Many clients qualify with zero medical exams or blood tests.
Estate & Wealth Protection IRC § 101(a) & Fla. Stat. § 222.14

Life Insurance Specifications

Death Benefit Taxation 100% Income-Tax Free
Asset Protection Creditor Immune (FL Law)
Underwriting Speed 24–48 Hr Accelerated
Living Benefits Critical / Chronic Riders
Needs Calculation: D.I.M.E. formula modeling Debt, Income 10-12x, Mortgage balance, and Education funds.
Comprehensive Coverage

Insurance Solutions Built for Your Real Life

Whether protecting personal wellness, securing your family’s future, or shielding your company workforce, our licensed advisors guide you through every choice.

American professional reviewing individual health insurance options Personal Coverage

Individual Health Insurance

Tailored medical coverage for self-employed individuals, 1099 contractors, and individuals seeking ACA Marketplace or private health plans.

  • ACA Marketplace & Subsidy eligibility checks
  • Essential preventative & emergency medical care
  • HMO & PPO preferred provider doctor networks
Explore Individual Plans
American family at home protected by family health insurance Family Protection

Family Health Insurance

Comprehensive medical, dental, and wellness coverage for growing families, ensuring dependents have access to trusted pediatricians and hospitals.

  • Pediatric checkups, immunizations & dental
  • Single shared or embedded family deductibles
  • Dependent coverage up to age 26
Explore Family Plans
Corporate workplace team collaborating under group health benefits Business & Employers

Corporate Health Insurance

Tax-advantaged group health plans designed for small businesses (SMEs) and mid-sized employers looking to recruit and retain high-performing talent.

  • Employer tax deductions & Small Business Credits
  • Tiered employee & family coverage tiers
  • Streamlined onboarding & compliance guidance
Explore Group Benefits
Parent holding child representing financial security through life insurance Financial Security

Life Insurance Coverage

Protect your loved ones against unforeseen financial hardship with reliable Term Life, Whole Life, and Universal Life policies customized to your mortgage and legacy goals.

  • Affordable 10, 20, or 30-year Term Life options
  • Permanent cash-value accumulation with Whole Life
  • Income replacement & estate preservation strategies
Explore Life Insurance
Active American seniors enjoying healthy retirement Medicare & Retirement

Senior Citizen Health Insurance

Specialized healthcare guidance for adults aged 65 and over navigating Medicare Advantage (Part C), Medicare Supplements (Medigap), and Part D prescriptions.

  • Out-of-pocket gap reduction with Medigap plans
  • Prescription drug coverage analysis (Part D)
  • Annual Enrollment Period (AEP) review assistance
Explore Senior Coverage
Unbiased Advocacy

Independent Agency vs. Captive Corporate Agent

Why do thousands of Florida policyholders switch to an independent brokerage? Because our duty of loyalty is to you, not to an insurance conglomerate.

Coverage & Advisory Factor Assertive Insurance (Independent) Captive Agents (Single-Carrier)
Carrier Options & Comparison ✓ Compares 10+ top-rated insurers ✕ Only sells 1 parent company’s policies
Fiduciary Loyalty ✓ Works exclusively for client’s best interest ✕ Bound by corporate parent sales quotas
Annual Rate Increases ✓ Re-shops the entire market to keep rates low ✕ You must accept the corporate rate hike
Florida Doctor & Hospital Networks ✓ Verifies multiple networks to keep your doctors ✕ Restricted only to single carrier directory
Claims Support & Advocacy ✓ Intervenes directly with insurer on your behalf ✕ Obligated to defend corporate insurer’s rules
Broker Fees for Clients ✓ $0 (100% Free Consultation & Service) ✓ $0 (Included in carrier premiums)
*All insurance rates are regulated by the Florida Office of Insurance Regulation (OIR). Premiums are identical whether you buy direct or through our independent agency.
The Assertive Advantage

Why Florida Clients Place Their Trust In Us

Insurance isn't one-size-fits-all. We act as your independent partner, analyzing plans from top carriers to pinpoint coverage that protects your health and wallet.

Personalized Guidance

No automated phone trees or robotic sales scripts. You speak with dedicated Florida advisors focused on your lifestyle and health history.

Broad Carrier Choice

As an independent agency, we are not locked into one insurer. We quote across premier rated carriers to find your optimal rate and network.

Clear Plan Terms

We eliminate fine-print confusion. We clearly explain deductibles, copayments, out-of-pocket maximums, and formulary coverage before you enroll.

Year-Round Support

Our commitment doesn't end when your policy takes effect. We assist with billing questions, provider network checks, and life changes.

Consumer Education

Demystifying Your Policy: 4 Numbers You Must Know

Insurance contracts are full of industry terms that directly affect your wallet. Understanding these four numbers ensures you are never caught unprepared.

01. Starting Threshold

Annual Deductible

The amount of covered medical expenses you pay out-of-pocket each calendar year before your insurer begins contributing toward treatment costs.

Real Scenario With a $3,000 deductible, you pay for doctor visits and medical tests until your cumulative bills reach $3,000, after which your plan activates cost-sharing.
02. Cost Sharing

Copay vs. Coinsurance

A copay is a fixed flat dollar amount per service (e.g. $25 per office visit). Coinsurance is a percentage split (e.g. insurer pays 80%, you pay 20%) after meeting your deductible.

Advisor Tip If you visit specialists or physical therapists regularly, choosing a plan with low fixed copays provides predictable monthly expenses.
03. Annual Ceiling

Out-of-Pocket Maximum

The ultimate legal spending limit for the year. Once your deductibles, copays, and coinsurance reach this threshold, your insurance pays 100% of eligible care.

Safety Benefit This is your catastrophic safety net, protecting your family finances against six-figure emergency hospitalizations or complex surgeries.
04. Provider Network

In-Network Doctors

Hospitals, specialists, and clinics contracted with your insurer at pre-negotiated rates. Seeking care out-of-network may trigger non-covered balance bills.

Assertive Guarantee Before enrollment, our Florida advisors personally cross-reference your primary care physicians and preferred facilities against carrier rosters.
Institutional Methodology

Our 4-Phase Client Advisory Framework

Independent insurance brokerage engineered for mathematical precision, statutory compliance, and lifelong policyholder advocacy. From initial census to active claim defense, here is how our Hollywood, FL practice represents your interests.

1
Phase 01

Census & Clinical Directory Audit

We analyze your household or corporate census, tax filing structure (1099, W-2, S-Corp K-1), and execute direct National Provider Identifier (NPI) cross-checks across Memorial Healthcare, Baptist Health, Cleveland Clinic Weston, and Mount Sinai rosters.

Deliverable: Verified in-network physician roster and underwriting census baseline.
2
Phase 02

Multi-Carrier Actuarial Traversal

Our licensed advisors scan 50+ approved filings across Florida Blue, Aetna CVS, UnitedHealthcare, Cigna, Oscar, Ambetter, and Mutual of Omaha. We model Advance Premium Tax Credits (IRC §36B), Cost-Sharing Reductions (CSRs), and Section 125 pre-tax cafeteria savings.

Deliverable: Precision tax subsidy optimization and net-premium calculation schedule.
3
Phase 03

Comparative Audit & Multi-Tier Selection

We deliver an objective side-by-side proposal detailing metallic tiers (Bronze to Platinum), embedded vs aggregate deductibles, prescription formulary tiers (1–5), coinsurance maximums, and outpatient facility copays with zero broker markups or consultation fees.

Deliverable: Side-by-side plan cost disclosure matrix with zero markup guarantee.
4
Phase 04

Direct Inception & Lifetime Claims Defense

We manage electronic application binding directly with carrier underwriting systems, expedite digital ID cards, configure payment processing, and provide ongoing claims defense, balance billing resolution under the No Surprises Act, and annual renewal re-shopping.

Deliverable: Active policy binding, digital ID issuance, and ongoing fiduciary advocacy.
Florida Insurance Code § 627.410 Rate Guarantee Rates are filed and legally fixed. Premiums are identical whether purchasing via broker or directly.
Detailed Advisory Methodology → Initiate Step 1 Discovery Call Advisor Desk
Practical Outcomes

Real Scenarios: How We Solve Florida Insurance Needs

Review real-world scenarios illustrating how our independent brokers match Florida residents with optimized coverage and substantial tax savings.

Freelance Professional Saved $315/mo

Miami Independent Consultant

A self-employed software consultant transitioning off COBRA was paying $680/month. We verified their projected 1099 taxable income and identified an ACA Silver plan with cost-sharing reductions and in-network access to Memorial Regional Hospital.

Net Premium: $365/mo with $0 preventive care
Family with Children Embedded Protection

Broward County Family of Four

A growing family with two young children needed comprehensive coverage with trusted pediatricians. We structured a family plan featuring embedded individual deductibles, shielding them from having to meet an entire $12,000 aggregate threshold for one child's broken arm.

Individual emergency capped at $2,500
Small Business Employer $16,800 Tax Savings

Hollywood Commercial Contracting Firm

A 14-employee commercial contractor was losing talent due to lack of health benefits. We implemented a level-funded group health plan paired with a Section 125 pre-tax payroll cafeteria plan, reducing employee turnover and delivering significant corporate tax deductions.

100% Tax-deductible business operating write-off
Key Deadlines

Florida Healthcare Enrollment Timelines

Understanding when you can enroll in Florida health insurance prevents lifelong penalties and ensures you aren't caught uninsured when you need medical care.

Annual Open Enrollment (Nov 1 – Jan 15) The universal period for all Florida residents to enroll, renew, or switch individual and family ACA health insurance policies for the upcoming year.
Special Enrollment Period (Year-Round via QLE) If you experience a Qualifying Life Event (loss of job coverage, relocation to Florida, marriage, birth of a baby, or divorce), you have 60 days to enroll immediately.
Medicare Initial Enrollment (IEP) Around Age 65 A 7-month window starting 3 months before your 65th birthday month, including your birthday month, and extending 3 months after.
Check Your Enrollment Eligibility

Are You Eligible to Enroll Today?

Speak with an advisor at our Hollywood, FL office. We can verify whether your circumstance qualifies for immediate guaranteed enrollment.

Relocated to Florida within the last 60 days
Loss of employer health coverage or COBRA expiry
Recent marriage, birth, or adoption of a child
Change in household income or subsidy bracket
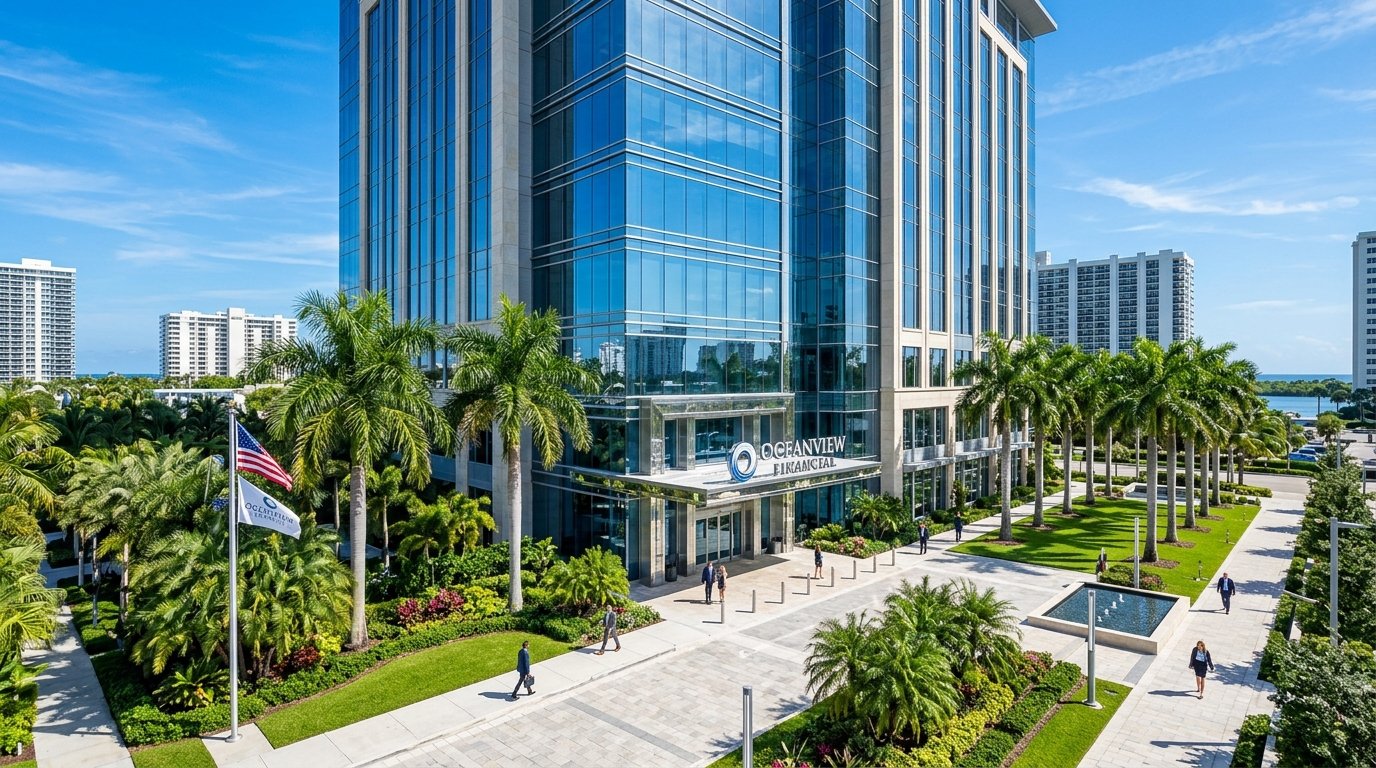
Assertive Insurance Hollywood FL headquarters corporate office plaza
Hollywood, FL Headquarters Campus Direct In-Person Client Consultations & Statewide Virtual Advisory
South Florida Headquarters

Rooted in Hollywood, Serving Across Florida

While massive web aggregators route your private medical data to distant out-of-state call centers, Assertive Insurance is proudly based right here in South Florida at 3440 Hollywood Blvd Ste 415, Hollywood, FL 33021.

Our licensed brokers understand the nuances of Florida healthcare: from local hospital systems like Memorial Healthcare, Baptist Health, Cleveland Clinic Florida, and Mount Sinai, to Florida Medicaid transitions, Medicare supplemental options, and small business workforce requirements.

In-Person Hollywood Office Consultations & Walk-Ins
Virtual Screen-Share & Statewide Telephone Advisory
Bilingual Advisory Support (English & Spanish)
Visit or Contact Office Learn Our Agency Story
Actuarial Intelligence

Florida Carrier Networks & Actuarial Value Matrix

Independent analysis of Florida Office of Insurance Regulation (OIR) approved metallic tiers, cost-sharing benchmarks, and South Florida hospital network penetration.

Metallic Plan Tier Actuarial Value (AV) Avg. Individual Deductible Primary Care Copay Prescription Formulary Target Consumer Demographic
Bronze Standard / HSA 60% (+/- 2%) $7,500 ?" $9,100 Ded. then 0% - $50 Tiers 1-2 Post-Deductible Catastrophic protection, high-earners utilizing HSA tax shields
Silver Benchmark (ACA Standard) 70% (Up to 94% with CSR) $0 ?" $5,800 $5 ?" $35 (Pre-deductible) Generics $3-$15 pre-deductible Individuals and families eligible for Cost-Sharing Reductions (100-250% FPL)
Gold Comprehensive 80% (+/- 2%) $1,500 ?" $2,500 $15 ?" $25 Copay Comprehensive low-copay formulary Predictable monthly medical utilization, ongoing chronic care
Platinum Elite 90% (+/- 2%) $0 ?" $750 $10 ?" $15 Copay Full formulary, minimal coinsurance High-frequency specialist visits, surgical schedules, maximum predictability
Commercial Level-Funded Group Custom Composite (75-88%) Custom ($1,000 ?" $3,500) $20 ?" $30 Copay Custom PBM carve-out options Florida employers (5-200 FTEs) seeking claims refund potential

South Florida Tri-County Hospital Network Integration

Florida Blue (BlueOptions / BlueCare) Comprehensive statewide network including Memorial Healthcare System, Baptist Health South Florida, and Broward Health.
Aetna CVS Health & UnitedHealthcare Expansive PPO and Open Choice networks with direct access to Cleveland Clinic Weston, Mount Sinai Medical Center, and Holy Cross.
Oscar Health, Ambetter & Molina Healthcare High-efficiency HMO networks optimized for value-based community clinical centers, telehealth-first primary care, and competitive copays.
Institutional Knowledge

Regulatory & Advisory Knowledge Hub

Authoritative guidance on statutory mandates, actuarial mechanics, and compliance frameworks governing Florida healthcare and insurance markets.

Network Architecture FL OIR Rule 69O-191

How do HMO, EPO, and PPO network mechanics diverge in Florida?

Network structure governs both monthly underwriting cost and geographic healthcare accessibility across Florida's tri-county region:

HMO (Health Maintenance Org): Enrollees designate an in-network PCP; specialist visits require referrals. No out-of-network benefits except emergency stabilization.
EPO (Exclusive Provider Org): Direct access to specialists without gatekeeper referrals, but strictly bounded within contracted network facilities.
PPO (Preferred Provider Org): Comprehensive multi-tiered coverage allowing in-network or out-of-network physician visits across state lines without referrals.
Advisory Note: If maintaining access to Cleveland Clinic Weston or Baptist Health doctors is mandatory, our advisors audit provider NPI numbers across carrier rosters prior to binding.
Statutory Enrollment 45 CFR § 155.410 / 155.420

What statutory windows govern Individual and Family plan enrollment?

Under federal ACA guidelines adopted by Florida, enrollment is regulated under strict calendar protocols:

Annual Open Enrollment Period (OEP): Runs November 1 through January 15 annually in Florida. Plans enrolled by Dec 15 start Jan 1; plans enrolled by Jan 15 start Feb 1.
Special Enrollment Period (SEP): 60-day window triggered by Qualifying Life Events (loss of group coverage, marriage, childbirth, interstate relocation to Florida).
Advisory Note: Standalone Dental, Vision, and Group Corporate health plans are exempt from OEP calendar constraints and can be established year-round.
Federal Subsidies IRC § 36B & ACA § 1402

How do Premium Tax Credits (APTC) and Cost-Sharing Reductions (CSR) function?

Tax credits lower monthly premiums, while Cost-Sharing Reductions (CSRs) fundamentally augment the plan's actuarial value:

Advance Premium Tax Credits: Calculated using modified adjusted gross income (MAGI) against the Second Lowest Cost Silver Plan (SLCSP) benchmark.
Silver CSR Variants: Household income between 100% and 250% FPL automatically enhances Silver plan actuarial value from 70% up to 87% or 94%, reducing deductibles to as low as $0.
Advisory Note: Selecting Bronze or Gold plans forfeits CSR eligibility even if income qualifies. Our advisors model exact tax credits on your behalf.
Corporate Commercial ERISA 29 U.S.C. § 1001 & IRC § 125

What structural models are available for Florida business group benefits?

Assertive Insurance architects multi-tiered health benefit models tailored to workforce demographic and claims history:

Fully-Insured Group: Fixed monthly premiums where carrier bears 100% underwriting risk. Ideal for turnkey risk elimination.
Level-Funded Stop-Loss: Blended hybrid where employer pays predictable monthly installments; surplus claims funds are returned to the employer at year-end.
Section 125 Pre-Tax POP: Federal tax shelter allowing employees to pay health premiums pre-tax, reducing employer FICA liabilities by 7.65%.
Advisory Note: Level-funded solutions often deliver 15% to 28% net savings for Florida companies with 10 to 150 participating employees.

Ready to Protect What Matters Most?

Contact our Hollywood, Florida office or request a customized insurance proposal online. Our guidance is always transparent, pressure-free, and personalized.

Request Free Custom Quote Call +1 (305) 709-6984
Office: 3440 Hollywood Blvd Ste 415, Hollywood, FL 33021 • Mon – Fri: 9am – 7pm EST